

Concora Credit
3.6

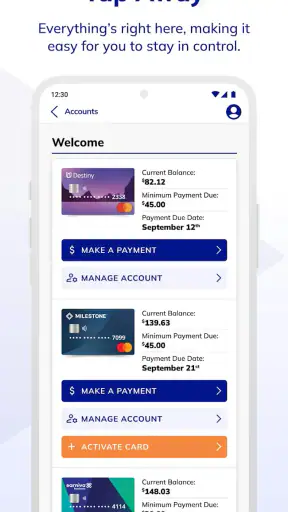
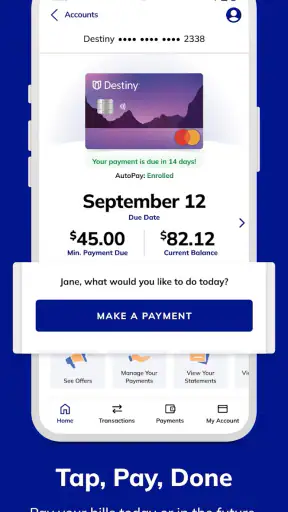
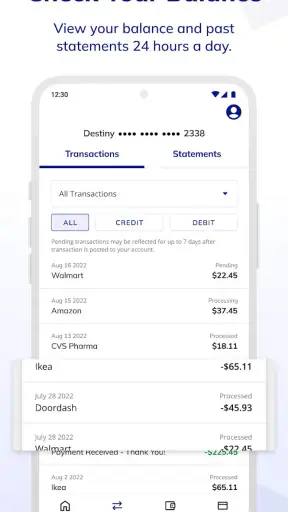
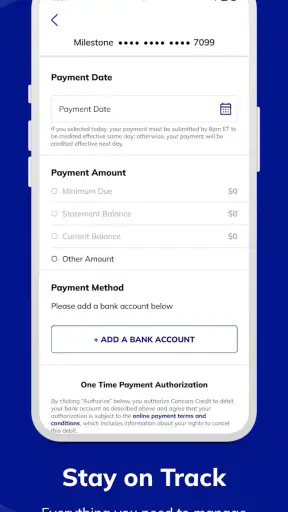
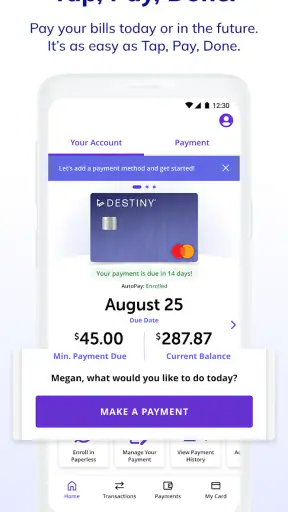
For someone who wants to check a credit account on a phone rather than keep track of every detail on paper, Concora Credit is a focused place to start. I’d think of it as an account-management app, not a general-purpose money dashboard: its usefulness depends on whether you have an account it supports and want a convenient way to keep an eye on it. That narrower purpose is worth understanding before you install it.
Readability and navigation
The app is a free finance app from Concora Credit, and its central job is managing credit account activity. That focus can make everyday checks feel more direct than opening a broad budgeting service full of tools you may never use. I would use it to get a quick account overview, then move to a more comprehensive finance app if I needed to combine several providers or build a household budget.
The store gives it an average rating of 3.6 from around three thousand ratings, alongside roughly one and a half thousand written reviews. I take that as a reason to approach it with practical expectations rather than assume every user’s experience will be identical. The app has been available since June 2023, and its current release is version 3.0.13. It has more than a million installs, is rated Everyone, and requires Android 7.0 or later. Those details make it accessible to many Android users, though the app’s value still comes down to whether its account tools fit your needs.
Keeping the account check simple
For me, the best reason to use a dedicated credit-account app is reducing the small bits of friction around routine account checks. If I’m deciding whether a planned purchase fits, I want to look at the relevant account without getting distracted by unrelated spending charts. A focused app can help turn that check into a quick habit: open it, review what matters, and close it before a small question becomes an hour of financial housekeeping.
That convenience is especially useful for someone who checks an account between errands or during a short break. I’d still treat the app as a view into account management rather than a substitute for reading account terms or confirming a consequential detail through the appropriate account channel. A quick glance is handy; decisions about repayment, fees, or a disputed transaction deserve a careful look at the exact information available to you.
Who is likely to find it useful?
I’d put this app on the shortlist for an existing Concora Credit customer who mainly wants a phone-based way to manage that account. It may also suit someone who prefers keeping account activity separate from a whole-finances tracker. If a single-purpose tool helps you stay attentive without encouraging constant checking, that can be a sensible fit.
By contrast, I would skip it if your main goal is to see balances across several unrelated banks, sort every purchase into categories, or plan a complete monthly budget. A general finance app is usually a better starting point for those jobs, while a bank’s own app may be more useful when you need a broad view of deposits, cards, transfers, and other services in one place. The important distinction is scope: this app is about managing the relevant credit account, not replacing every financial tool on your phone.
A realistic way to work it into the day
Imagine you’re about to make a purchase and want to check your credit account before committing. I’d open the app, review the account information that’s available, and use that as one input in the decision rather than relying on memory. Later, when you have more time, you can review the account in greater detail and make sure the purchase still fits your wider budget. Keeping those two steps separate helps prevent a quick mobile check from standing in for thoughtful planning.
A useful habit is to decide in advance what you want each visit to answer. For example, you might check whether the account needs attention, then leave. That makes a credit app less likely to become an endless refresh ritual. If your concern is a charge you don’t recognize or a detail that could affect a payment decision, take the time to inspect the relevant account information carefully instead of assuming a brief overview tells the whole story.
Making a short visit more useful
One practical trade-off with a dedicated account app is that it can make the relevant information easier to reach while leaving your overall financial picture elsewhere. I’d use that division intentionally: let this app handle its specific account, and keep a separate budget or note for commitments across other accounts. This avoids treating a partial view as if it were a complete balance-sheet picture.
If you share household expenses, another sensible approach is to agree which person checks the account and how you’ll communicate anything that needs attention. The app can support an individual’s account routine, but it cannot by itself establish a shared household plan. A simple weekly check-in or a separate household budget may be more useful than expecting one credit-account app to coordinate everyone’s finances.
I’d also avoid making the app the only place where you remember important obligations. A calendar reminder or your normal payment-planning method can serve as a backup, especially if you sometimes change phones or have a day when mobile access is inconvenient. That is not a knock on this particular app; it’s a good rule for any tool that helps you monitor money without replacing your own record-keeping.
Motor and sensory considerations
For people who find repeated tapping tiring, a focused task can be easier to approach than a sprawling finance interface, but the real experience depends on how the controls appear and behave on an individual device. I’d try the routine you expect to use most—opening the account, locating the information you need, and returning to the main screen—before relying on it for a time-sensitive task. If small controls, dense text, or a particular screen flow are uncomfortable, your device’s display and interaction settings may help, but they cannot fix every design barrier.
People who prefer less screen time may appreciate having one clear reason to open the app and then stop. Someone sensitive to frequent alerts, on the other hand, should be deliberate about which notifications they allow if those controls are available in their setup. I wouldn’t assume that a finance app will suit every sensory preference automatically; the best test is whether its actual prompts and screens feel manageable in your everyday environment.
Using it in different situations
At home, you can take time to review account details without rushing. On a commute or while standing in a queue, a quick check may be convenient, but I’d avoid handling sensitive financial information where other people can easily see your screen. If you use a shared device, think carefully before leaving an account open, and make sure you know how to end your session in the way your device and app provide.
Connectivity and interruptions also shape the experience of any account-management app. If you need information urgently, don’t assume a screen will remain current after a connection issue or a long pause; reopen the account and verify what it shows before acting. For a decision that cannot wait, use another established way to contact the account provider rather than relying on a mobile screen that has stopped responding.
Where the convenience has limits
A credit-account app is not the same thing as a credit bureau report, financial adviser, or full budgeting system. I would not treat an account view as a guarantee about what another lender will see, nor assume it replaces reviewing official account statements. Its strongest role is making routine account management more accessible from a phone; broader financial planning still needs a broader source of information.
It is also worth remembering that a smooth app experience and the underlying account experience are separate things. If something about an account needs a formal explanation or resolution, an app screen may not be enough on its own. I’d keep a note of the question, check the relevant account details, and use an appropriate support route when a simple mobile check cannot settle it.
Questions to settle before relying on it
The first question is whether this is the right app for your account. Since its purpose is managing Concora Credit accounts, I’d confirm that the account you want to handle belongs in that setup before making it part of your routine. If you’re looking for a tool to connect unrelated accounts, choose a service designed around that wider job instead.
Next, consider what you expect to do from your phone. If you only need a convenient account-management option, a dedicated app may be enough. If you need detailed spending analysis, shared budgeting, or a combined view of multiple financial institutions, compare those needs against a broader finance app before committing your time to a workflow that cannot cover them.
Finally, ask yourself whether mobile access genuinely makes the task easier. If you prefer paper records, use a desktop, or find phone-based account checks stressful, there is no need to force this app into your routine just because it exists. A good finance tool is one you can use comfortably and consistently, not one that adds another source of alerts or worry.
Inclusive verdict
My view is that Concora Credit makes the most sense as a practical mobile companion for people who already need to manage a relevant credit account. Its narrow purpose can be an advantage for quick, focused checks, while its limits matter for anyone looking for all-in-one money management. The app is free, but convenience alone does not make it the right choice for every account holder or every way of interacting with a phone.
I’d recommend trying it if a dedicated account tool fits your routine, then judging it by how easily you can complete the tasks that matter to you. Pay attention to readability, tapping effort, interruptions, and whether the account information is clear enough for your decisions. If those basics work for you, it can earn a place in your financial routine; if they don’t, a different access method or a broader service may be a better fit.
So, you’ve probably heard of Concora Credit if you’ve been looking for a way to manage your finances right from your smartphone. I decided to give it a whirl and see what all the buzz was about. Spoiler alert: it’s pretty nifty! Here’s my take on it.
First Impressions and User Interface
When I first downloaded Concora Credit, I was immediately drawn to its sleek and intuitive design. It’s like the app developers knew exactly what we chaotic budgeters needed. The layout is clean without being too simplistic, which I appreciate. The navigation is straightforward, with all the main features just a tap away. No need to dig through endless menus—hallelujah!
Getting Started
Setting up was a breeze. I’m not a fan of apps that make you jump through hoops just to get started, and thankfully, Concora Credit wasn’t one of them. You just need to link your bank accounts, and voila, you’re good to go. The app supports a wide range of banks, so chances are, yours is on the list. What I loved was how the app categorized my transactions automatically. It was fascinating to see where my money was actually going—turns out, I spend way too much on takeout!
Main Features
Let’s talk about the features that make this app stand out. One of the coolest things is the budgeting tool. It’s not just about tracking expenses; it helps you set realistic budgets based on your spending habits. The app sends you friendly reminders if you’re nearing your budget limits. I mean, who doesn’t need a little nudge every now and then?
Another feature worth mentioning is the credit score tracker. It’s like having a financial advisor in your pocket. You get insights into what’s affecting your score and tips on how to improve it. Plus, the app updates your score regularly, so you’re always in the know.
Security and Privacy
Now, let’s get real for a second. When it comes to financial apps, security is a big deal. I know I was a bit skeptical at first about linking my bank info. But Concora Credit uses bank-level encryption and multi-factor authentication, which put my mind at ease. They’ve got a solid privacy policy, ensuring your data is safe and sound.
Usability Across Devices
Whether you’re team Android or team iOS, you’re in luck. The app runs smoothly on both platforms. I tested it on my phone and tablet, and it was a seamless experience across the board. It syncs in real-time, so you can switch devices without missing a beat. Pretty convenient, right?
Customer Support
If you ever run into any issues, Concora Credit has a responsive customer support team. They offer support via chat and email, which is great because sometimes you just need a human to help out instead of scrolling through FAQs. I had a minor question about syncing accounts, and their team got back to me in no time.
In conclusion, if you’re looking for a way to get a handle on your finances without all the stress, Concora Credit might just be the app for you. It’s got everything you need to track spending, manage budgets, and even boost your credit score. Plus, it’s super easy to use, so even if you’re not the most tech-savvy, you’ll be navigating it like a pro in no time.
So, why not give it a shot? You might just find it’s the financial sidekick you didn’t know you needed.
3.6
1.47K Reviews
Pros
- User-friendly interface enhances navigation.
- Real-time credit score updates.
- Secure data encryption for user protection.
- Customizable alerts for credit changes.
- Comprehensive credit report insights.
Cons
- Limited support for international users.
- Requires stable internet connection.
- Some features behind paywall.
- Occasional app crashes reported.
- Limited customer service response.


